LINE
Add me
William Huang
Add me and send a message about what you would like to discuss.
Add on LINE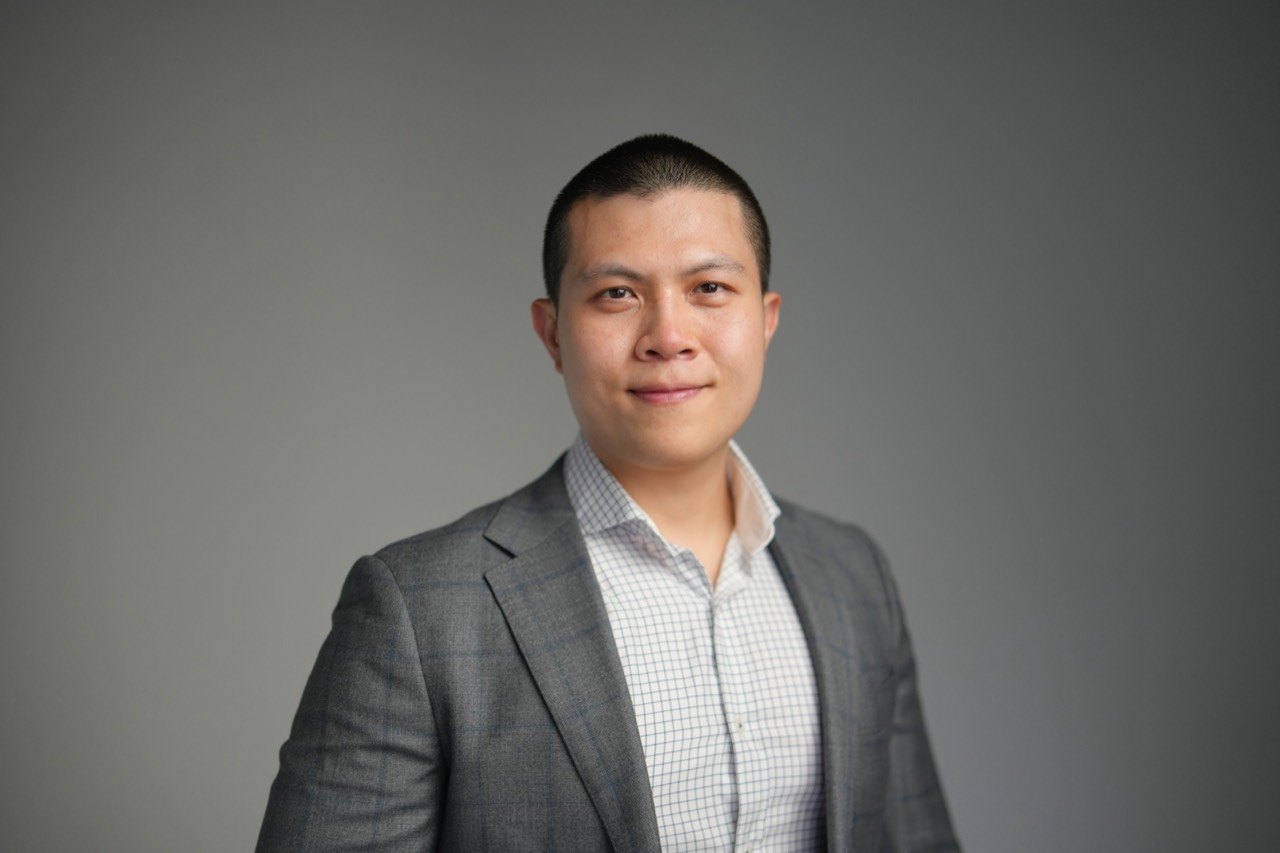 WilliamAustralian mortgage brokerBook a chat ↗
Start with what your current lender can offer, then compare the costs and benefits of refinancing.
Common questions to help you understand and compare refinance options.
Work out how long interest and fee savings take to cover the switching costs.
Compare the same balance and remaining term, then include one-off costs such as discharge and application fees. A lower repayment is not necessarily a saving; it could reflect a longer term. This is an estimate and changes in rates or repayments will affect it.
It is worth assessing, but check the break cost first.
Paying out a fixed loan early may incur break costs. Ask your current lender for the amount, include it with other switching costs, and compare refinancing now with waiting until the fixed period ends.
Not necessarily. You may simply be taking longer to repay the loan.
For example, extending a remaining 20-year term to 30 years may reduce monthly payments but increase total interest. Compare the same remaining term first, then consider whether you need a cash-flow adjustment.
A fixed rate offers certainty for a set period; a variable rate can change with the lender.
Fixed loans may limit extra repayments and have break costs. Variable rates can rise or fall. We can also discuss splitting the loan between fixed and variable, depending on your need for certainty and flexibility.
It is an account linked to your home loan. Eligible balances reduce the amount used to calculate loan interest.
For example, a $500,000 loan with $50,000 in a 100% offset may be charged interest on $450,000. The loan principal itself has not fallen by $50,000. The money is usually accessible, but withdrawals reduce the offset benefit. Account fees and product conditions also matter.
Not always. Check how the lender calculates them.
To keep the same annual repayment total, use monthly repayment × 12 ÷ 26. Paying half a monthly repayment every fortnight instead gives 26 half-payments, equivalent to 13 months. These are different methods; the actual debit depends on the lender’s arrangement.
Compare the overall cost, not just the rate difference.
Check whether your existing lender can improve the loan, then compare alternatives over the same remaining term. Include discharge, application, valuation, registration and settlement fees, possible LMI and fixed-rate break costs. Consider features, break-even time and offer conditions. If the term is extended, compare total interest too.
Not automatically. Equity is not cash you can simply withdraw.
A valuation, loan-to-value assessment and repayment-capacity check are usually needed. A larger loan also changes repayments. Tell me the purpose and amount, and we can explore the options.
Yes. We can first see what your existing lender can offer.
Depending on the lender’s process, I can help negotiate or explain how to request a review. If the lender is not on my panel, I cannot negotiate on your behalf and will let you know. We can still compare refinance options. Any rate change is the lender’s decision.
Start with your loan balance, rate, remaining term and statements.
Tell me what you want to improve. If refinancing makes sense, I will request the relevant identification, income, debt and expense documents. Comparisons are from my lender panel, not the entire market.
Usually not. Once you choose an option, we submit a full application.
The new lender reassesses your finances and property valuation. Further documents or approval conditions may apply. I will then help with the loan documents and discharge authority for you to check and sign.
Keep making the existing repayments until settlement.
The lenders and their representatives coordinate settlement. I track the payout of the old loan and establishment of the new one. Rely on lender confirmation for payout and debit changes; we also check the new account setup and actual repayments afterwards.
Yes. We still need to check the account setup and repayments afterwards.
Within 1–3 business days of settlement or a rate change, I check the rate, repayment account, offset link, payment date and amount. After the debit, I check the actual payment. Around three to six months later, we review the rate and product as appropriate. You can contact me again when your needs change.
Yes. Use the same booking link for all three.
Choose a convenient time and tell me which type of loan you want to discuss.
This site is for finding answers. It does not accept loan documents.
If you proceed with an application, I will explain what documents are needed and how to provide them. You do not need to enter personal information to read these answers.
I may not have covered that question yet. Try another keyword or ask me directly.
New FAQs checked: 27 October 2026 · Conditions need to be confirmed when you apply
General information only. Actual conditions depend on your circumstances, lender and contract. Still have questions? Ask William ↗
These official sources help explain general lending concepts. Individual conditions still need to be checked.
Explore our refinancing guides, or search for a topic below.
Try another keyword, or get in touch and tell me what you would like to know.
Talk to William ↗I’m based in Melbourne and help clients across Australia with home, car and personal loans. Many of my clients prefer to discuss their options in Chinese; this site is available in English too.
I often hear similar questions in consultations, so I put them here for you to browse when you need them. Everyone’s circumstances are different. If you still have questions, we can talk them through.
Book a 30-minute loan consultation ↗Opens William’s booking page on Cal.comBook a time and tell me what you would like to know. We can talk about home loans, car loans or personal loans.
Scan a QR code with your phone, or use the buttons below to start a conversation.
William Huang
Add me and send a message about what you would like to discuss.
Add on LINE
William Huang
Open a chat and tell me what is on your mind.
Open WhatsApp